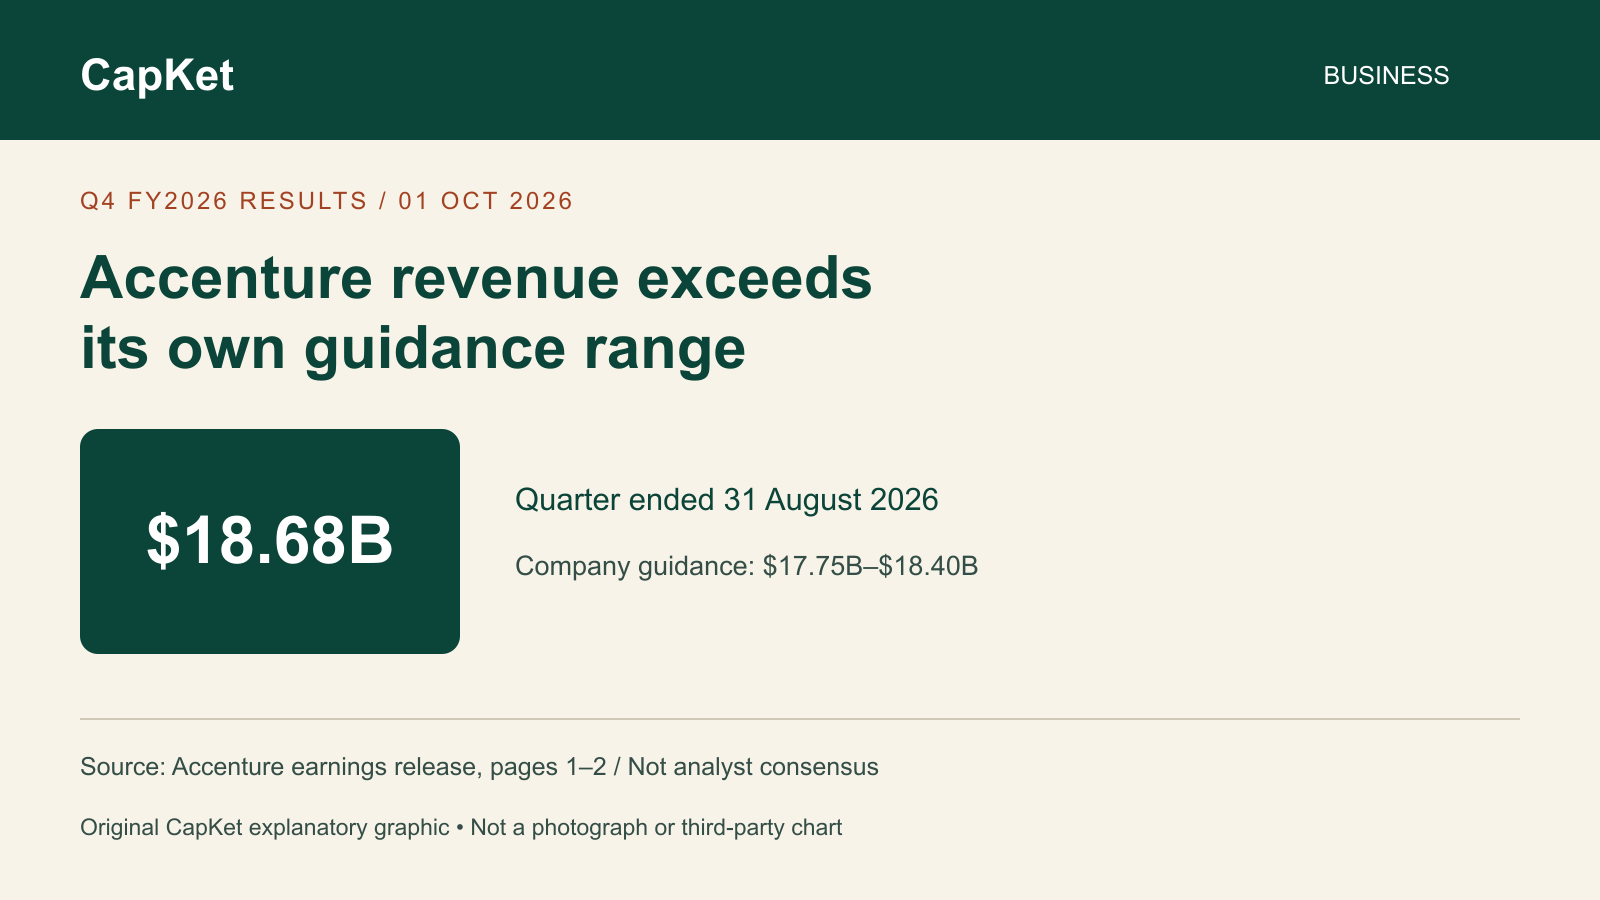
Accenture reported fourth-quarter revenue of $18.68 billion on October 1, exceeding its own forecast range of $17.75 billion to $18.40 billion. The results cover the fiscal quarter and year ended August 31, 2026—not the calendar quarter ended September.
What the revenue result shows
Revenue increased 6% in US dollars and 7% in local currency from the comparable quarter. Full-year revenue reached $74.2 billion. Local-currency growth separates the reported business comparison from currency translation effects.
The quarterly result was $280 million above the top of management’s range, calculated from the published figures. This is a comparison with Accenture’s guidance, not a claim that it beat analysts’ forecasts. CapKet has not verified a consensus estimate or a share-price reaction.
Why the profit comparison matters
Quarterly diluted earnings per share under US GAAP were $3.29. Accenture reports a 46% increase against the prior year’s GAAP figure, but 9% against the prior year’s adjusted figure. Its adjustments exclude business-optimization costs.
CapKet analysis: Those percentages answer different questions. A reader comparing underlying performance should examine which costs were excluded and whether the same basis is used in both periods. The larger percentage alone is not a complete explanation of the business’s progress.
What comes next
Accenture forecasts fiscal 2027 revenue growth of 3% to 6% in local currency. That range is management’s outlook, not a completed result.
For readers following IT spending, the useful next test is whether later revenue and profitability support that outlook. Avoid treating one supplier’s results as proof that every technology buyer or competing services company is experiencing the same conditions. Our Kyndryl application-dependencies explainer looks at a separate question: how companies assess the work involved in modernization.
Primary evidence: Accenture’s official fiscal 2026 results, pages 1–3, checked October 1, 2026 at approximately 20:45 IST. This report is informational, not an investment recommendation.